The legal bill is visible. The rent you never collect and the market growth you miss are not.
Research date: 27 September 2026 | Worked examples are illustrative and pre-tax
Imagine walking away from a Budapest apartment in 2015 because the legal bill, transfer tax and first repairs felt too expensive. You keep the money liquid and wait for a cleaner entry point. The decision feels cautious.
A decade later, the fees you avoided look very small beside the market you missed. Between 2015 and the fourth quarter of 2025, Hungary’s house-price index rose by about 290%, while rents increased by 109%, according to Eurostat. This does not mean every apartment quadrupled in value, or that the next decade will repeat the last. It reveals a cost that rarely appears on a completion statement: time outside the market.
The hidden costs of buying property are real. But so are the hidden costs of not buying: lost rent, reduced purchasing power, a larger future deposit and years of capital growth that cannot be recovered later.
In Brief
- Visible buying costs are usually paid once. The opportunity cost of waiting can compound for years.
- Property can build wealth through rent, capital appreciation, mortgage repayment and active value creation.
- EU house prices rose 64.9% between 2015 and the fourth quarter of 2025, but the strongest markets moved much further.
- The answer is not to buy anything at any price. It is to choose a durable asset and give it enough time to work.
The Cost Investors See Is Not Always the Largest One
Taxes, legal work, registration, surveys and essential repairs deserve a place in every purchase model. They affect the capital required on day one. Yet they are visible, finite and usually known before completion.
Opportunity cost behaves differently. It grows quietly. Each year outside the market can mean another year without rent, another year without debt reduction and another rise in the price of the asset the investor still hopes to buy.
| Visible cost | Usually appears | The less visible alternative |
|---|---|---|
| Tax and registration | At purchase | A higher entry price after waiting |
| Legal and technical work | Before completion | A decade without rental income |
| Repairs and furnishing | Before letting | No opportunity to improve the asset |
| Mortgage fees | At financing | No tenant-supported debt repayment |
The point is not that buying costs do not matter. It is that a EUR 5,000 invoice should not dominate a decision whose ten-year outcome may be measured in rent, equity and appreciation.
Property Has More Than One Return Engine
A savings account has interest. A bond has a coupon. A share may provide dividends and capital growth. A well-selected residential property can combine several return engines inside one asset.
- Rent can provide recurring income from a real household need.
- Capital appreciation can increase the value of the underlying asset over time.
- Mortgage repayment can convert part of the monthly cash flow into investor equity.
- Active ownership can lift rent or resale value through renovation, energy upgrades, furnishing or better management.
Long-run academic evidence is not a promise about the next purchase, but it gives useful context. Research covering 16 advanced economies from 1870 to 2015 found that long-run housing returns were comparable with equity returns, with lower aggregate volatility. The authors also warn that asset-level results and costs matter. See The Rate of Return on Everything.
Leverage adds another dimension. A mortgage can allow an investor to control a larger real asset while retaining liquidity, although the financing must remain affordable under weaker conditions. Our comparison of buying with cash or a mortgage looks at that trade-off in more detail.
What Five Years of Waiting Can Cost
Consider a simple hypothetical property bought for EUR 250,000. It produces net operating income equal to 4% of the purchase price, while its value grows by 3% a year. These are assumptions, not forecasts. They exclude financing, tax and selling costs.
| Five-year illustration | Calculation | Result |
|---|---|---|
| Net rental income | EUR 10,000 × 5 years | EUR 50,000 |
| Estimated value after five years | EUR 250,000 × 1.03⁵ | EUR 289,819 |
| Illustrative capital gain | EUR 289,819 − EUR 250,000 | EUR 39,819 |
| Combined income and gain | Before tax, finance and sale costs | EUR 89,819 |
The investor who waits does not automatically lose EUR 89,819. Prices may rise more slowly, rents may disappoint and liquid savings may earn interest. The model shows something simpler: waiting is an active financial position. It gives up the property’s return engines and needs its own expected return to justify the delay.
Europe Keeps Moving While Buyers Wait
Between 2015 and the fourth quarter of 2025, house prices increased by 64.9% across the EU. The differences between markets were much larger: Hungary rose by about 290%, Portugal by 180%, Lithuania by 168% and Bulgaria by 157%. Over the same period, EU rents increased by 21.8%, and rents rose in every member state, according to Eurostat.
That is not evidence that European property only moves in one direction. Finland recorded a small price decline over the same comparison, and individual cities, neighbourhoods and buildings can diverge sharply. It is evidence that waiting for “Europe” to become cheap is not an investment strategy. Europe is a collection of local markets with different supply, income, migration and financing dynamics.
The opportunity lies in finding the market where demand is durable and the future is not yet fully priced. Our framework for comparing European property markets provides the next step.
Hungary Shows the Opportunity Cost Clearly
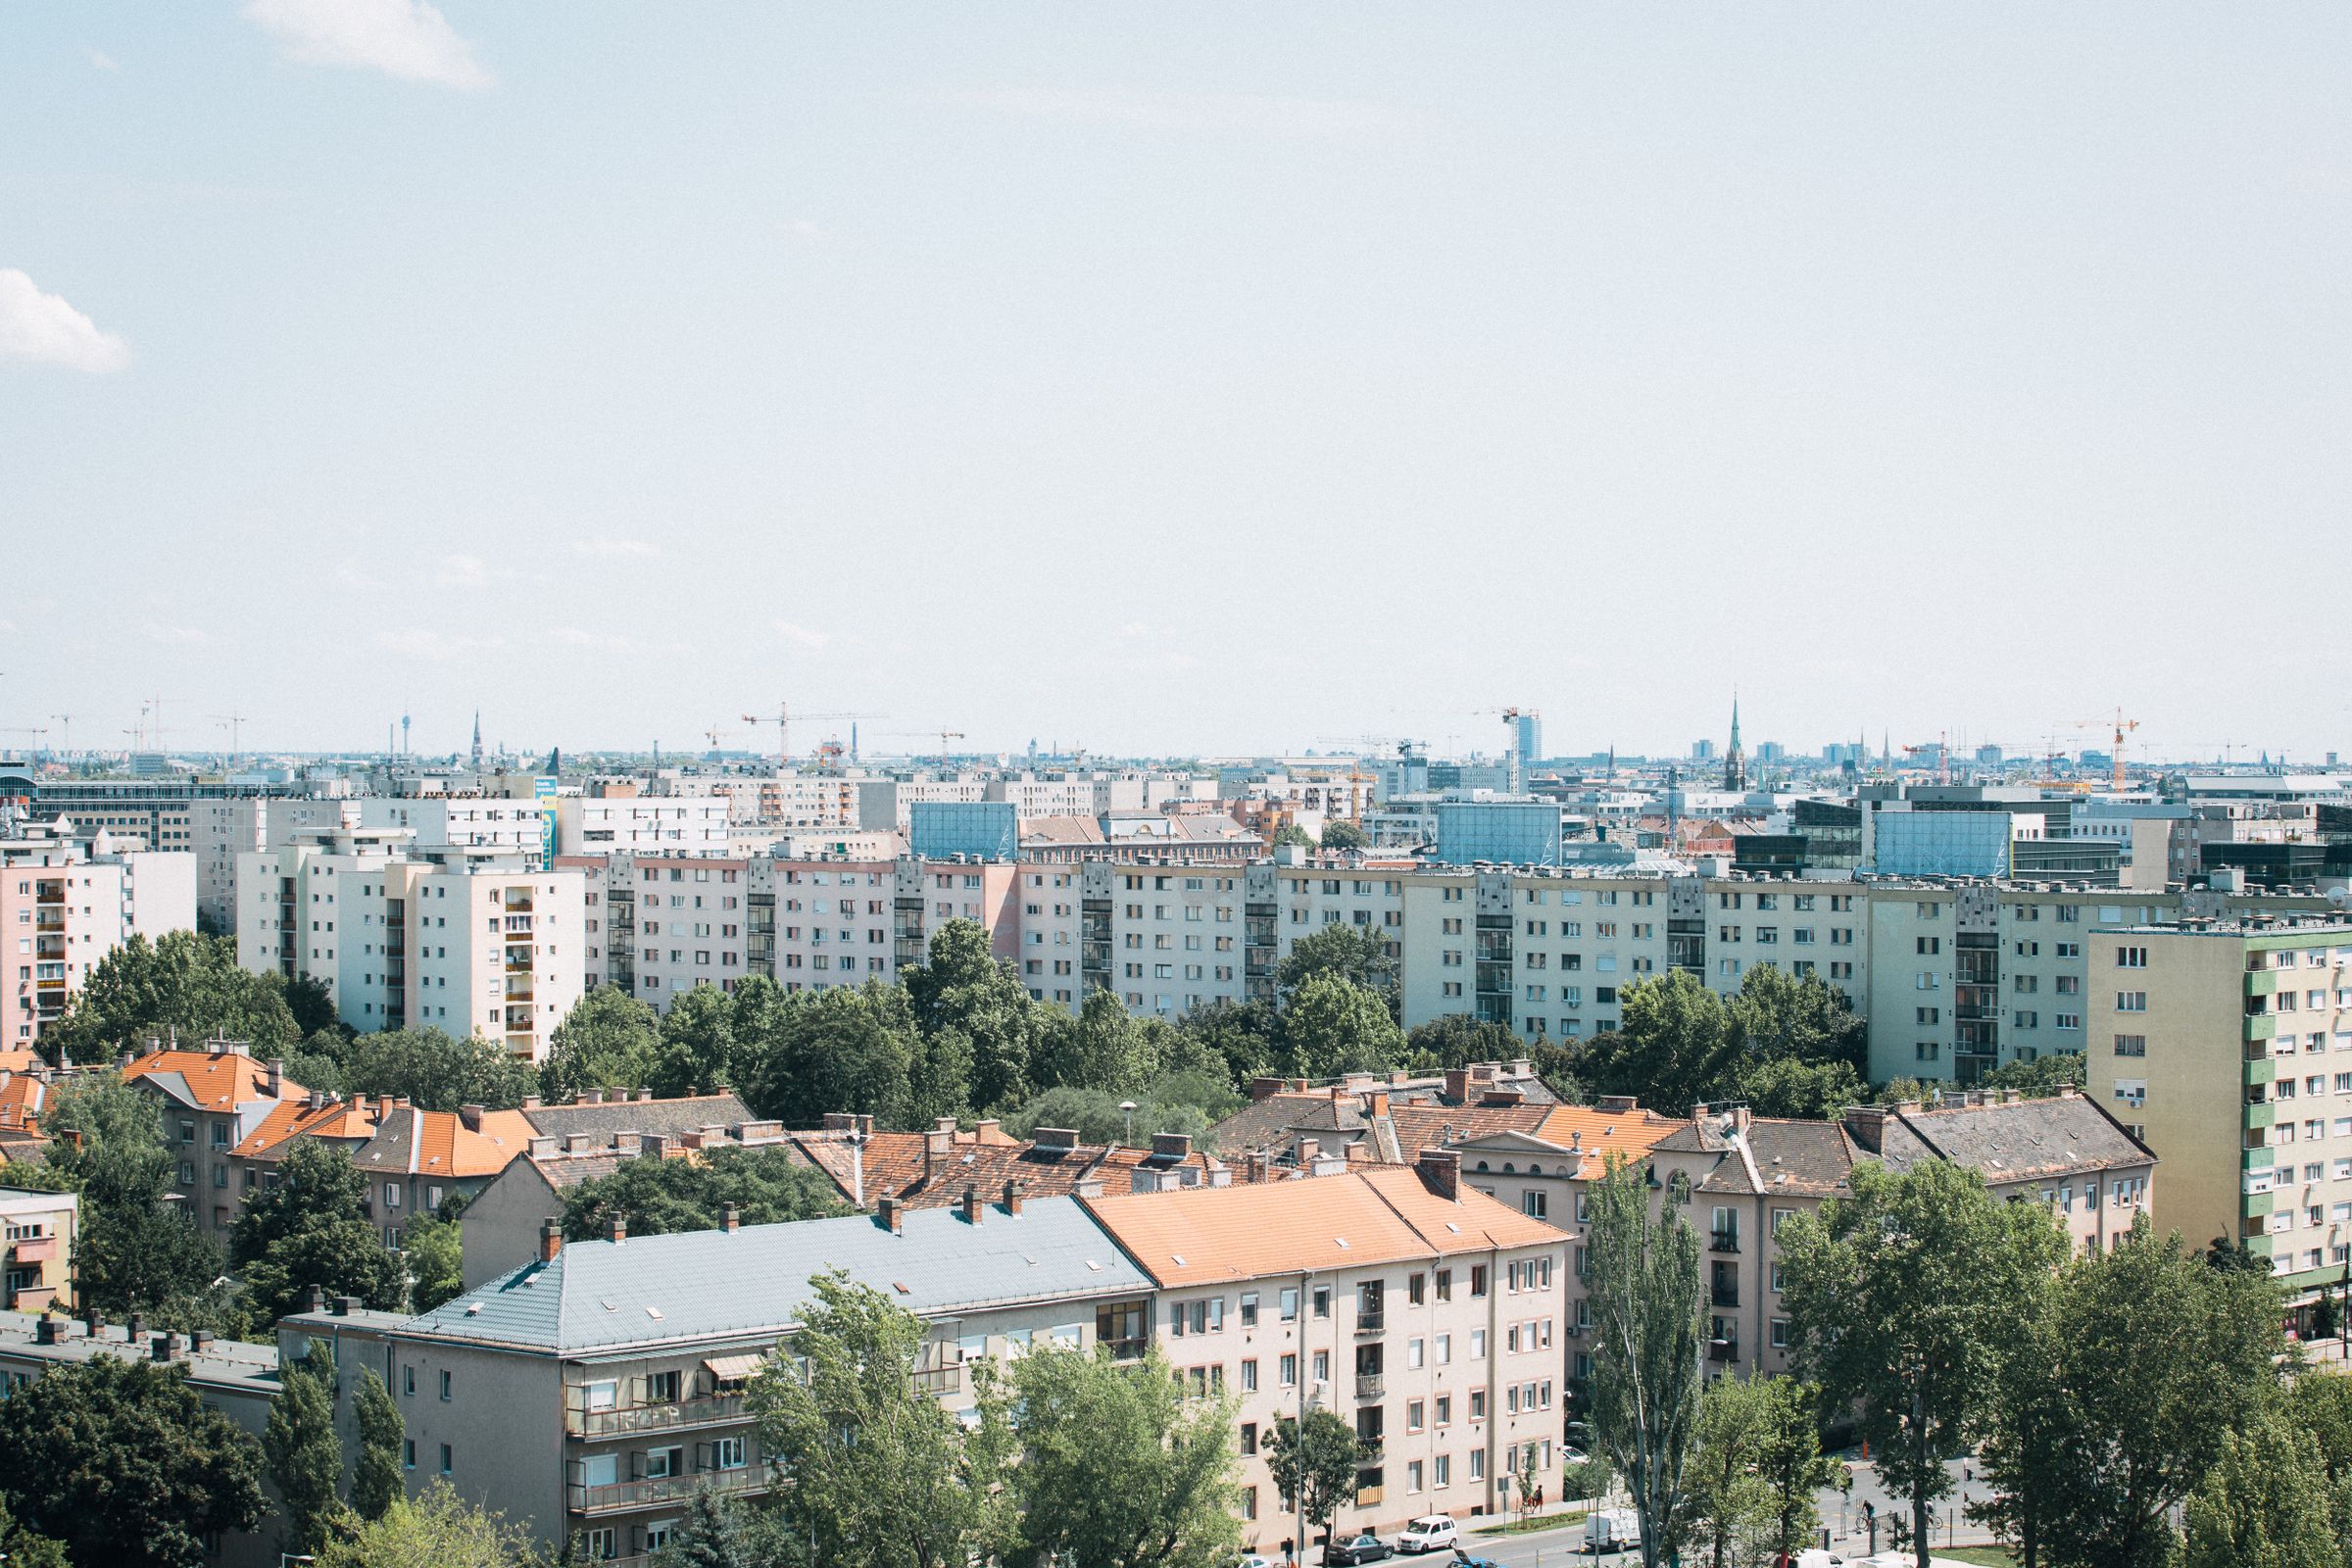
Hungary is an unusually vivid example. The Magyar Nemzeti Bank reported that national house prices rose by 23.5% in 2025, equivalent to 19% after inflation. Budapest also entered 2026 with a substantial expansion in new housing supply. For an investor, this creates a more interesting market, not a simpler one: momentum is strong, but selection and entry price matter.
The same MNB report estimated that prices were more than 20% above the level justified by fundamentals nationally at the end of 2025. That warning should not erase the opportunity. It should direct capital towards liquid locations, useful floor plans, realistic rents and a longer holding period rather than speculative short-term buying.
Euro adoption could become another long-term catalyst through lower currency friction and deeper financial integration, but it does not belong in the base case. The European Commission states that Hungary has no official target date and the forint is not yet in ERM II. For now, euro adoption is optionality, not a forecast.
For a tangible view of current purchasing power, see what EUR 250,000 can buy in Budapest.
Property Compared With the Alternatives
| Asset | Income | Growth potential | Leverage and control | Main strength |
|---|---|---|---|---|
| Idle cash | None | None | None | Immediate liquidity |
| Deposits and bonds | Interest or coupon | Usually limited | Little investor control | Predictability |
| Diversified equities | Dividends | High long-term potential | Limited direct control | Liquidity and diversification |
| Residential property | Rent | Asset and rent growth | Mortgage plus value creation | Multiple return engines in a real asset |
Property is not the winner on liquidity or instant diversification. Its advantage is the combination. The investor can own a useful asset, receive income, use secured finance, improve the property and hold it through the daily noise of public markets.
The European Central Bank’s medium-term inflation target is 2%. Even when policy succeeds exactly, money that earns less than inflation loses purchasing power over time. The comparison is therefore not between a risky property and perfectly stable cash. It is between different risks, different return engines and different uses of time. See the ECB monetary policy strategy.
Buying Costs Matter Less When Time Has Room to Work
The correct response is not to ignore tax, legal work, repairs or financing fees. It is to place them inside the full holding-period economics. A high-friction purchase intended for resale next year may be fragile. The same one-off costs can become proportionately smaller across ten years of rent, debt reduction and capital growth.
This is why headline yield alone is not enough. Use the difference between gross and net rental yield to test today’s income, then ask how the asset can become more valuable over the holding period.
Do Not Wait for Perfect Certainty
Property rewards preparation, but perfect certainty is normally available only in hindsight. A disciplined investor does not chase any rising market. The investor buys when four conditions are present:
- the location has durable tenant and resale demand;
- the price and rent work without relying on an optimistic catalyst;
- the financing and cash reserve can survive weaker conditions; and
- the holding period is long enough for income and asset growth to compound.
Return to the buyer who walked away in 2015. The saved legal bill was real. So was the decade of rent and market growth that followed. The most important hidden cost was never printed on an invoice.
The largest hidden cost of buying property may be the time spent not owning it.
Get Place for Capital’s European property analysis in your inbox. We focus on the markets, strategies and long-term forces behind better real-estate decisions.
This article is for general educational purposes. It is not personalised financial, tax, lending or legal advice.