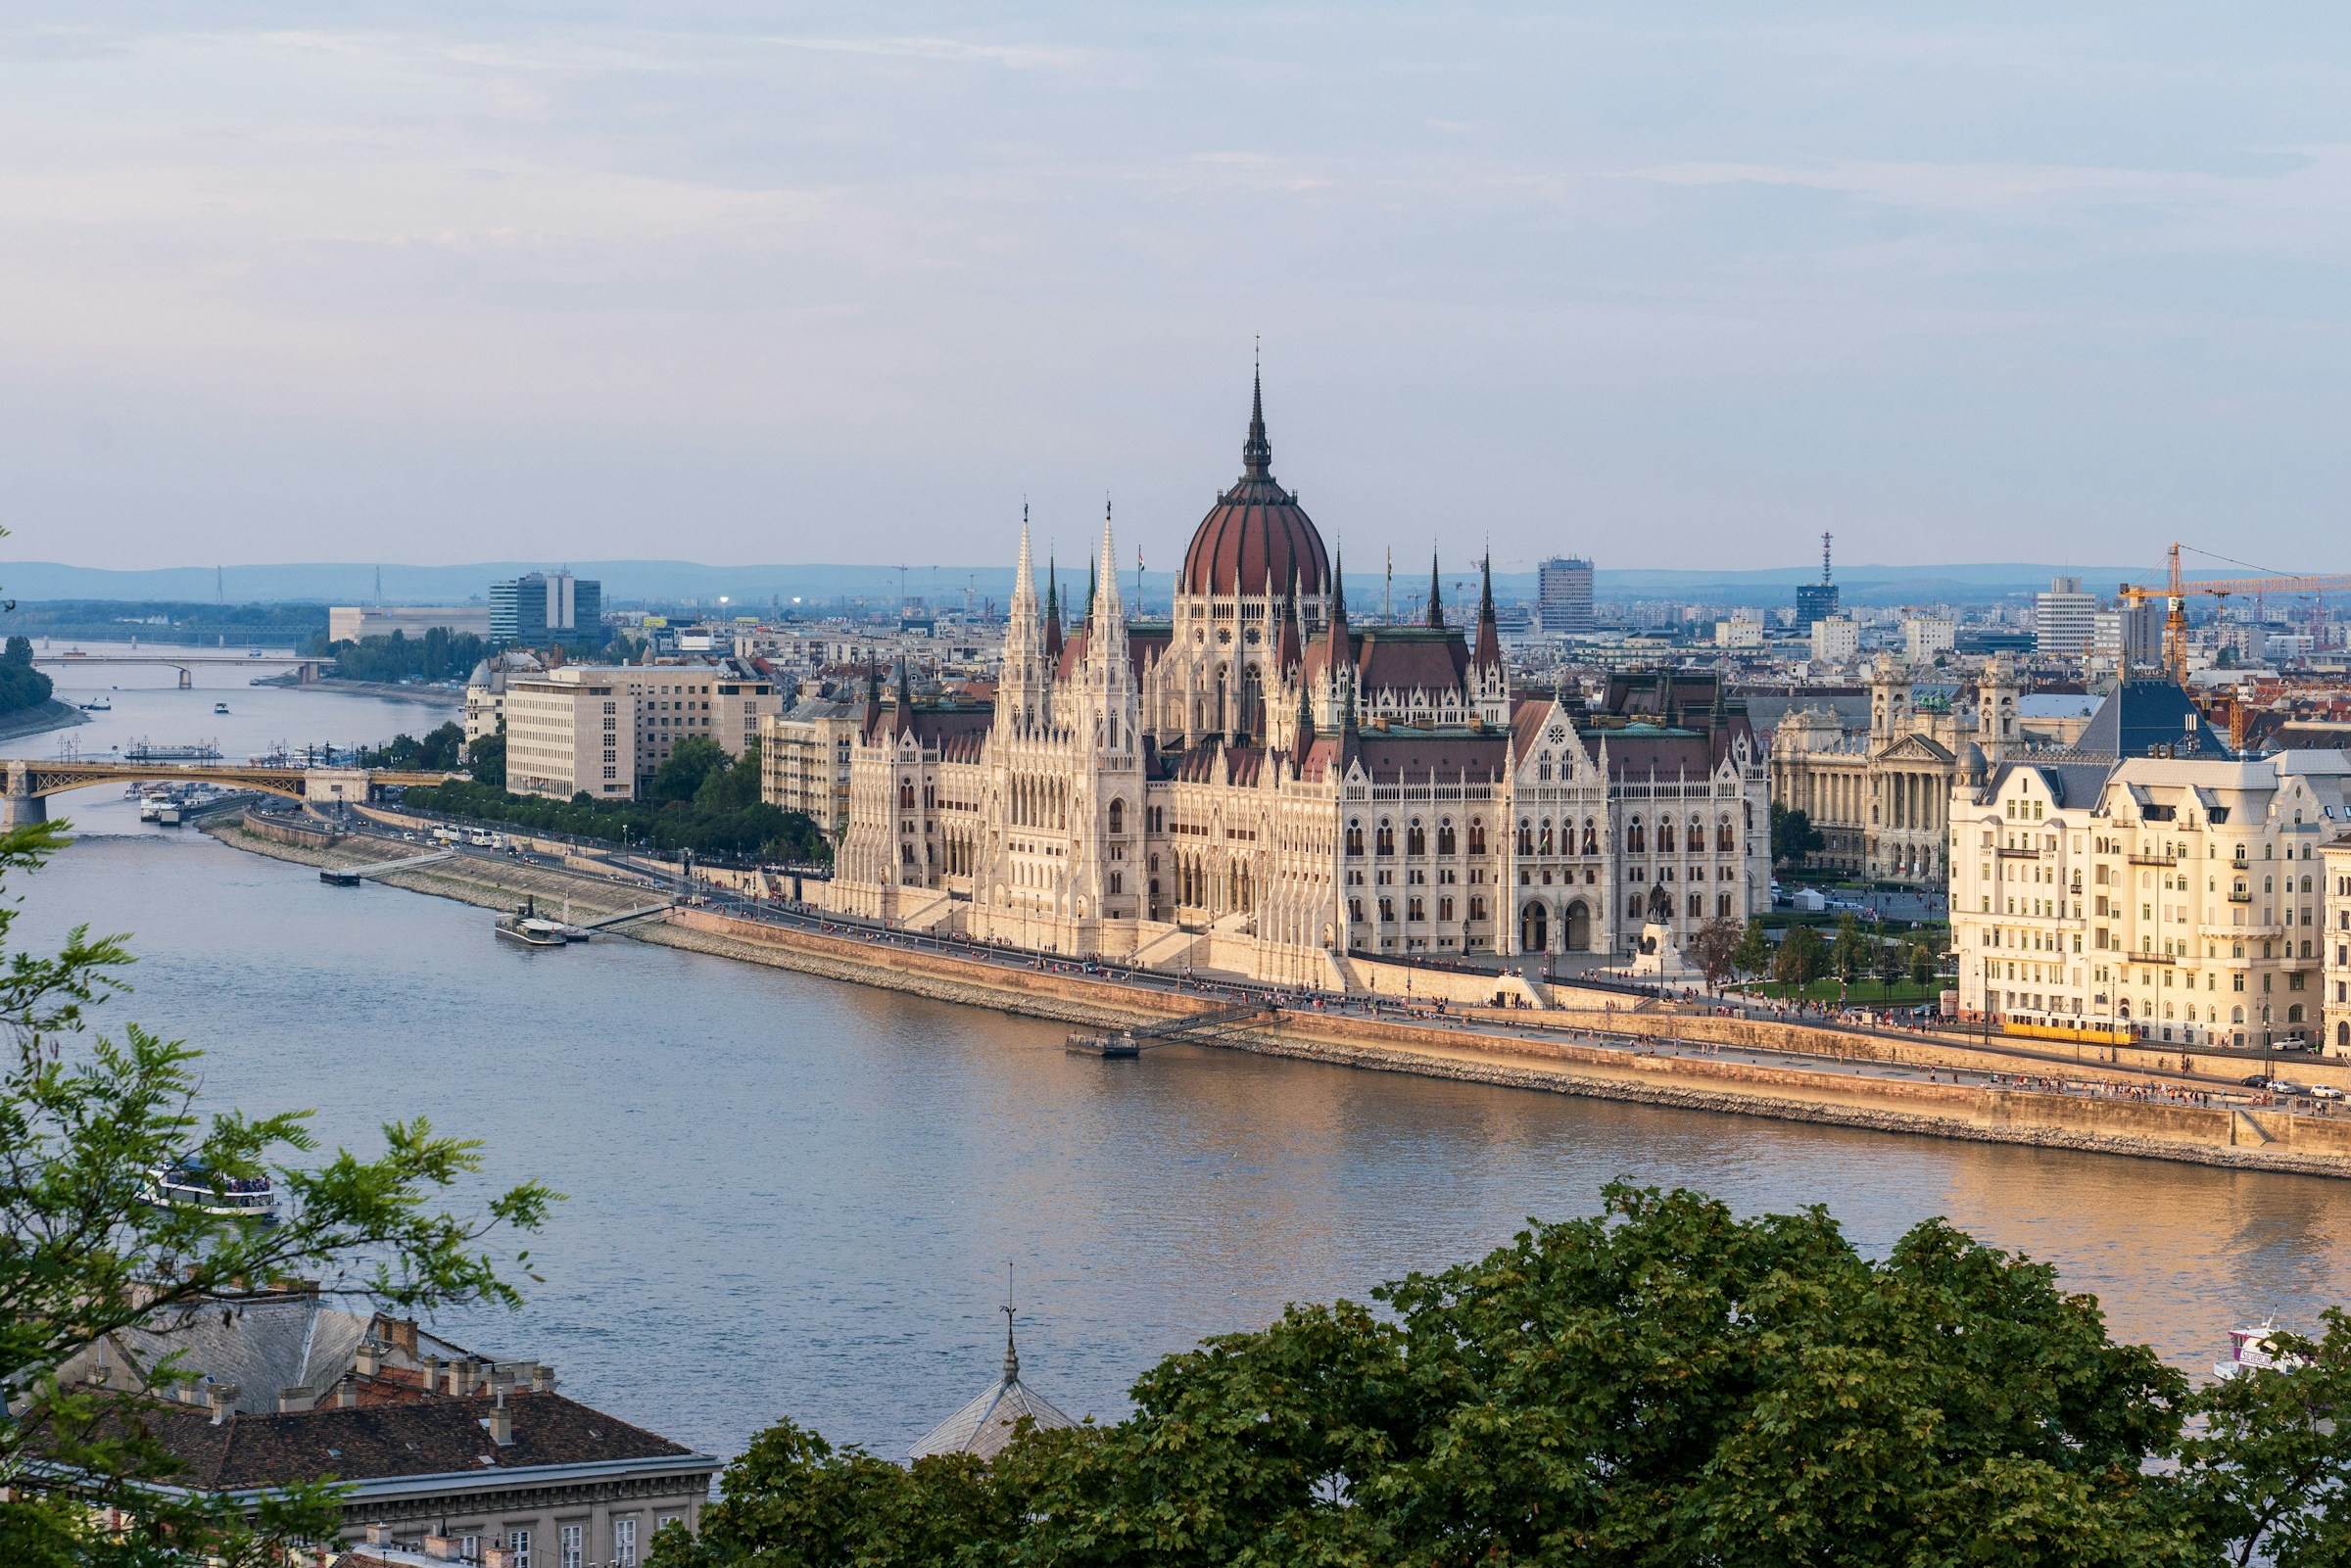
Budapest, Warsaw, Bucharest and Prague offer four distinct property-investment profiles: Budapest emphasises choice and value-add potential, Warsaw income and tenant depth, Bucharest lower-cost entry with heavier due diligence, and Prague scarcity and capital preservation.
Research date: 30 September 2026
A regional comparison changes as soon as an investor looks beyond the headline yield. Warsaw can produce more rent relative to price. Bucharest can look cheaper still. Prague offers genuine scarcity. The relevant question is how entry price, tenant demand, exit liquidity and building-level risk fit a particular strategy.
These four markets lead on different dimensions. Budapest gives an international buyer a broad choice between central historic stock, renovation opportunities, completed apartments and new projects. Warsaw offers a deep professional tenant market, Bucharest stronger headline income, and Prague a scarcity-led defensive case. The trade-offs matter more than a single universal ranking.
Four Markets, Four Trade-Offs
| Market | Distinctive strength | Main caution |
|---|---|---|
| Budapest | Value, asset choice and improvement potential | Currency exposure and uneven new-build delivery |
| Warsaw | Income, tenant depth and completed new-build choice | Higher entry prices and project-level oversupply |
| Bucharest | Headline yield and lower-cost entry | Building quality, seismic checks and market transparency |
| Prague | Scarcity, stability and long-term capital preservation | High prices and thin net yields |
There is no universal order. A hands-off buyer may prefer Prague, while an income-led buyer may choose Warsaw or Bucharest. Budapest may suit a private investor seeking a liquid apartment with several exit routes and room to add value.
Budapest: Value, Optionality and Asset Improvement
Budapest sits in the useful middle of the regional market. September 2026 asking data from Global Property Guide put its average gross residential yield at 4.84%. That is below Warsaw and Bucharest but comfortably above Prague, before vacancy, management, maintenance, tax and common costs.
The city also offers more variety at one budget. An investor can choose a renovated central resale, a tired historic apartment with a value-add plan, a conventional residential district or a new-build project. Prague gives fewer inexpensive routes into a strong location, while Warsaw’s most liquid employment corridors have become materially more expensive.
The local detail is easy to misread. Budapest’s monitored new-build market had 9,747 available homes in Q3 2026, but only 9% were complete; 78% were scheduled for 2027 or 2028, according to Budapesti Lakáspiaci Riport data reported by Pénzcentrum. A large pipeline is therefore not the same as immediate rental competition. It does, however, give buyers leverage in individual projects, especially where sales have slowed or a developer needs to move a specific layout.
The Hungarian National Bank recorded historically high new-build availability while investors became more cautious as yields compressed. That combination rewards inspection and negotiation rather than market-wide optimism.
Budapest’s additional advantage is optionality. A weaker forint would make unchanged local prices cheaper for a new euro-funded buyer, while strong transport, universities and international employment continue to support a broad tenant base. Currency movement can also reduce the euro value of rent and resale proceeds, so it should be treated as upside, not guaranteed return. See our full Budapest property market outlook.
Warsaw: Income and Tenant Depth
Warsaw has the region’s deepest mainstream income case. Current asking examples commonly support gross yields of roughly 4.3% to 5.8%, and the city’s employment base, universities and internal migration create a large rental pool.
The opportunity is not simply demand. It is completed supply. CBRE and Tabelaofert.pl counted 3,344 finished new apartments still unsold at the end of Q2 2026. A completed unit removes delivery risk and lets the buyer inspect the exact light, outlook and finish. In slower projects, the concession may appear in parking, storage, fit-out or payment terms rather than the advertised apartment price.
National Bank of Poland data also showed a 10.2% gap between the average Warsaw new-build asking price and achieved transaction price. That makes the list price poor evidence of value. Warsaw’s central and inner-district entry prices are higher, while its large development pipeline makes project selection critical. Read the detailed Warsaw prices, yields and outlook.
Bucharest: High Yield, Higher Due Diligence
Bucharest has the most attractive headline income figures in this shortlist. September 2026 asking data put the city’s average gross residential yield at 6.91%. Colliers found first-half apartment transactions only 2% below the previous year, a more resilient result than Romania’s 9% national decline.
The discount comes with work. Building age, legal status, energy performance and seismic exposure can change the real investment case. Bucharest’s municipal seismic-risk authority, AMCCRS, publishes a building list, but the absence of an address from that list is not proof of safety. A World Bank review noted that the public data did not capture the full extent of vulnerability and that the city had started a wider assessment programme.
That is the local edge investors should price. A central apartment can show an excellent gross yield because the building risk, financing difficulty or future consolidation cost has already been discounted. Bucharest suits a buyer with strong local legal and technical support. Investors who prioritise easier execution over headline yield may prefer a market with broader building choice and resale liquidity.
Prague: Scarcity and Capital Preservation
Prague is the strongest scarcity story and the weakest income story. Its average gross residential yield was about 3.54% in Q2 2026 asking data. The IMF’s 2026 Czech housing analysis described a structural imbalance in which demand has persistently outpaced construction constrained by slow permitting and municipal fragmentation.
Scarcity can support long-term values, but investors pay for it upfront. The useful local lesson is that ten extra square metres do not always create extra rent. Achieved-rent analysis cited in our Prague guide found that a well-planned 50 m² one-bedroom apartment can rent for roughly the same total amount as a 60 m² unit with the same room count, even though the larger home costs materially more.
Prague can suit a preservation-first buyer who accepts a low initial yield. Investors seeking more income or flexibility may prefer a lower-priced entry market; the trade-offs are detailed in our Prague investor guide.
How to Choose Between Them
- Choose Budapest when asset choice, liquidity and value-add potential matter most.
- Choose Warsaw when current income and a deep professional tenant market matter most.
- Choose Bucharest only when the higher yield compensates for intensive legal, technical and building-level checks.
- Choose Prague when scarcity and capital preservation matter more than cash flow.
Do not compare gross yields without using the same rent definition and the same treatment of common charges. Our guide to gross versus net rental yield explains what needs to be deducted before two markets are genuinely comparable.
Central and Eastern Europe remains attractive because the capitals combine economic convergence, constrained housing supply and lower entry prices than many Western European cities. The best opportunity is not the market with the largest percentage in a portal table. It is the city where the investor can buy a specific, liquid apartment without relying on optimistic rent, perfect occupancy or a future buyer ignoring the building’s weaknesses.
The four markets answer different investor questions. Budapest emphasises optionality, Warsaw current income, Bucharest headline yield and Prague scarcity. The strongest choice depends on the buyer’s strategy, risk tolerance and ability to execute at building level.
Free investor briefing: Download the free investor briefing.
This article is for general educational purposes and is not personalised investment, legal or tax advice.