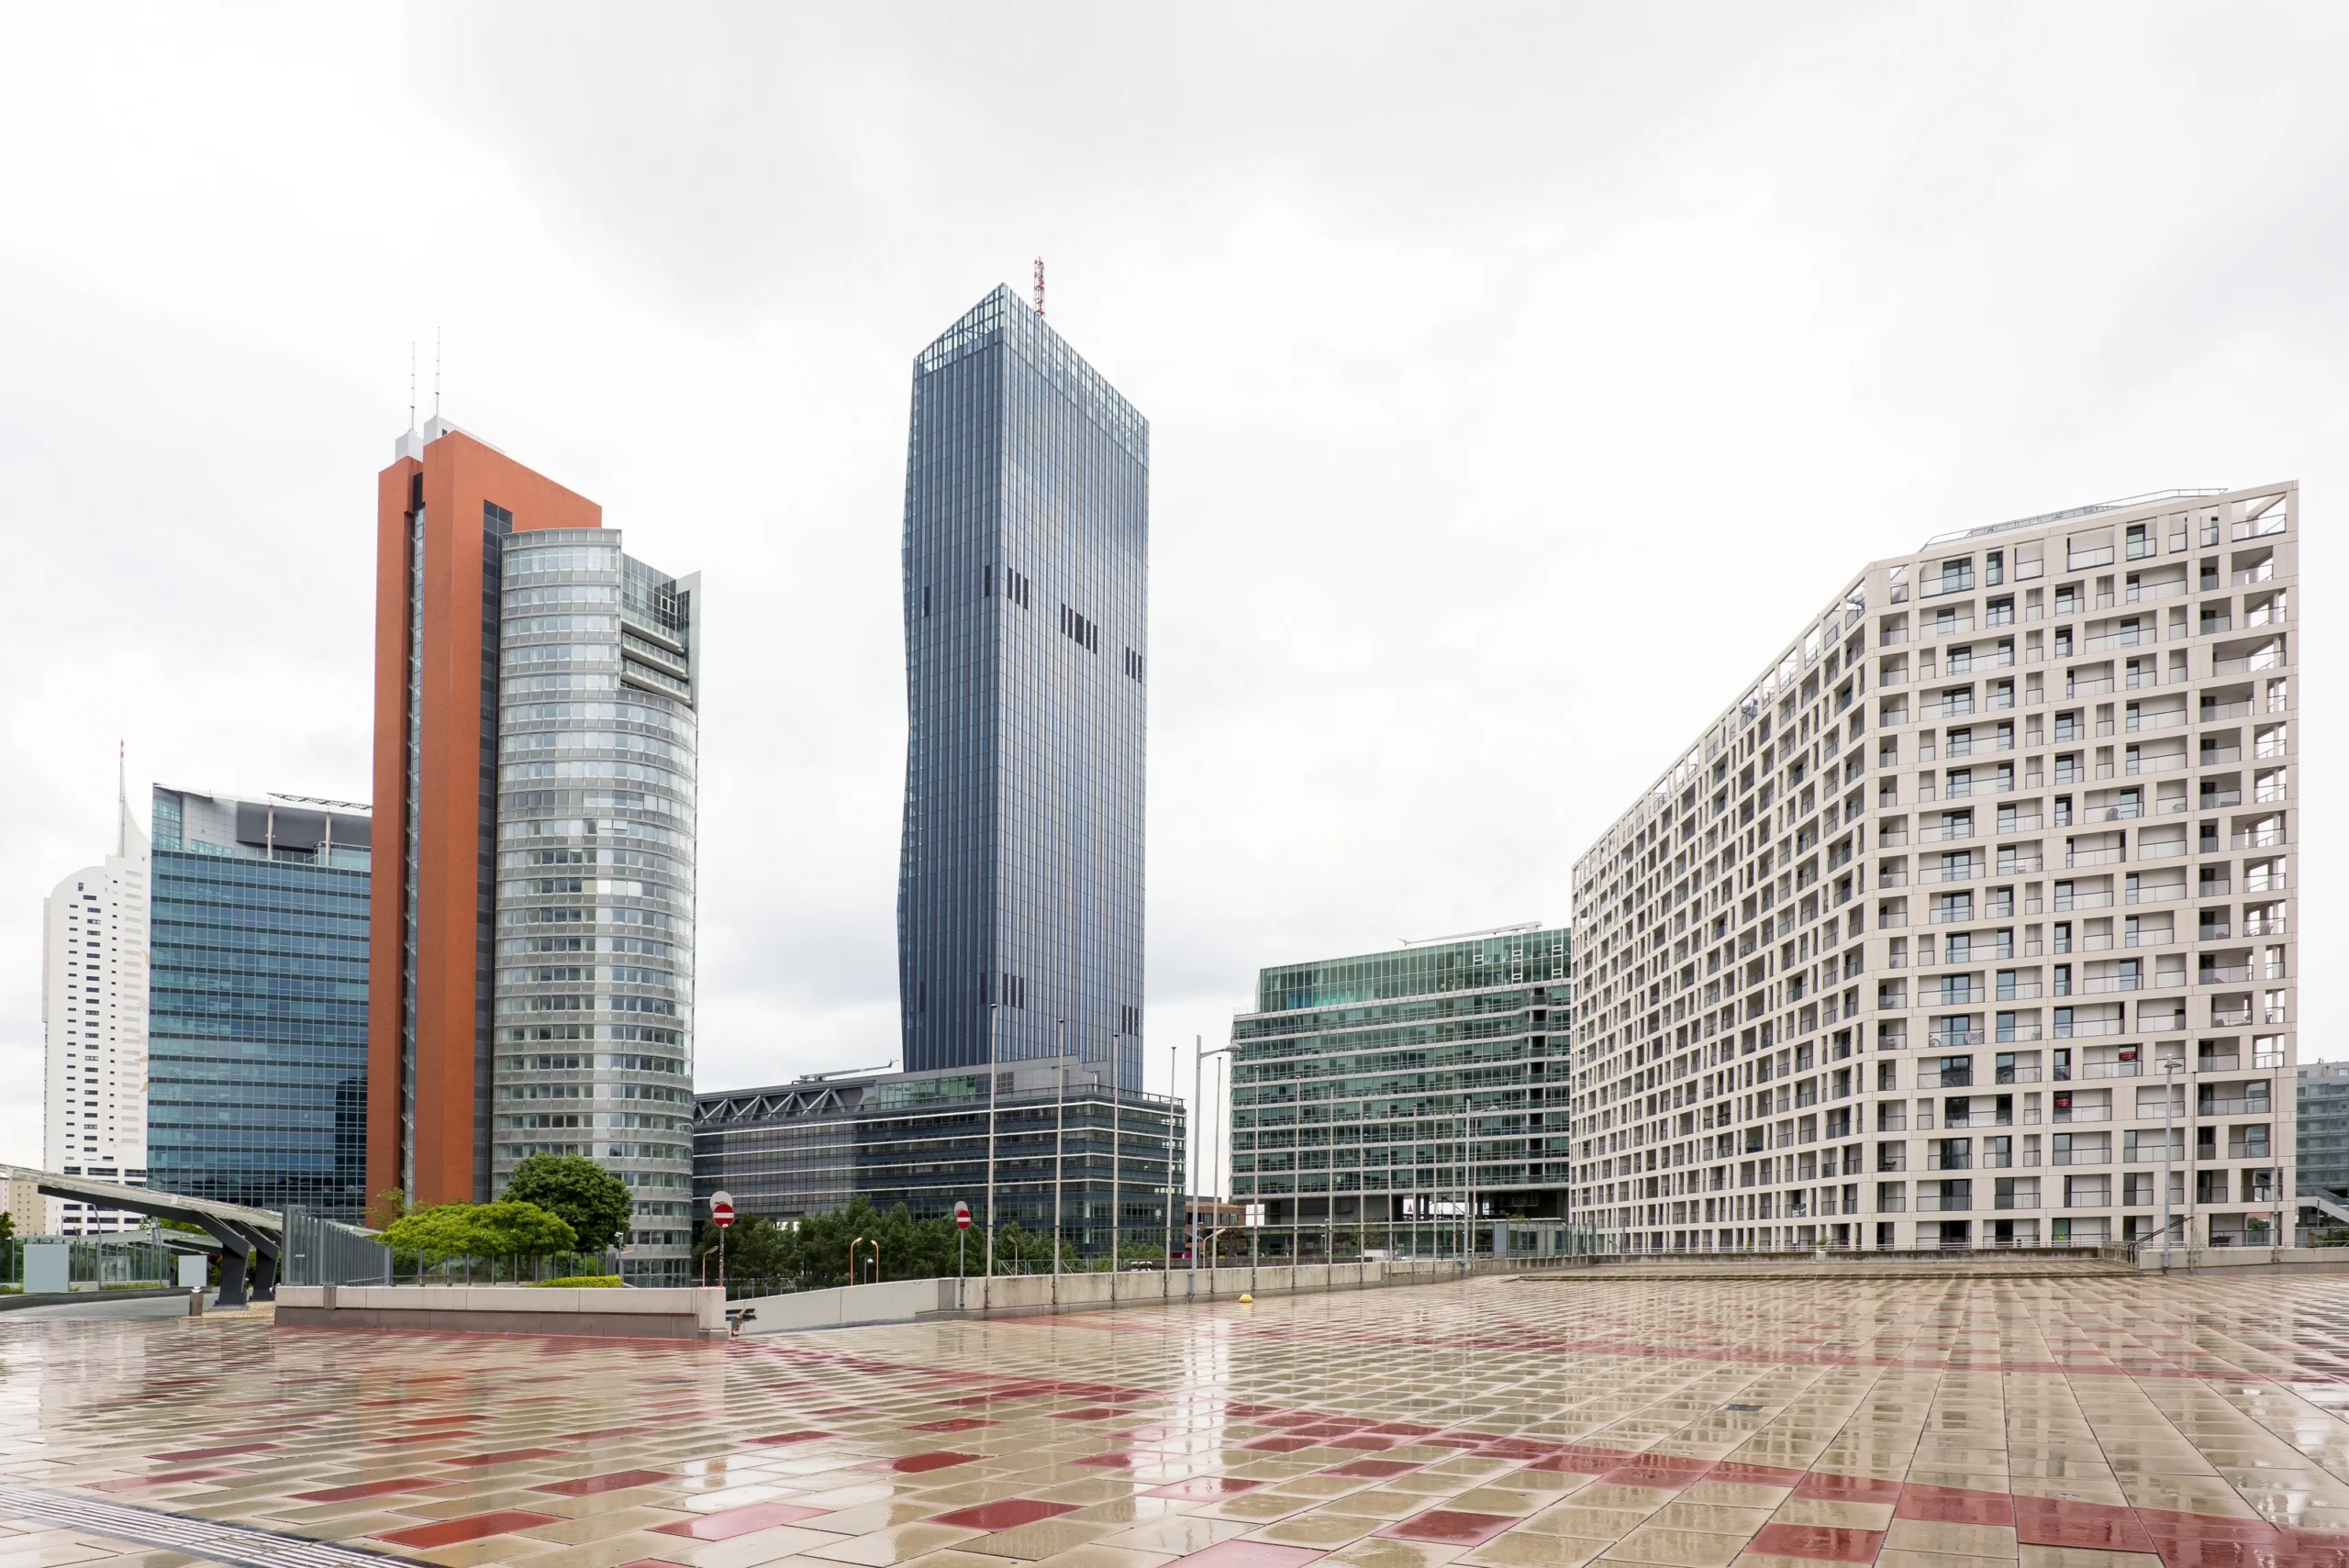
Warsaw combines strong rental demand with a rising supply of completed apartments, creating a market where investors can still earn attractive gross yields but should negotiate project by project.
Research date: 27 September 2026
Warsaw ended Q2 2026 with 3,344 completed new apartments still unsold. They represented 20.5% of developer inventory, a record share. In a capital known for fast sales and persistent housing demand, that is the number investors should notice.
It does not signal a citywide crash. Sales remained above their five-year quarterly average and new-build transactions were 44.3% higher than a year earlier in the National Bank of Poland's Warsaw study. It does mean that buyers can separate strong projects from stock that has reached completion without finding an owner.
Kurz zusammengefasst
- The National Bank of Poland's Q2 Warsaw study recorded an average new-build asking price of PLN 18,488 per m² and a transaction price of PLN 16,783, a 10.2% gap.
- New-build supply rose 14.2% quarter on quarter to more than 13,500 units in the NBP sample, while a separate CBRE series counted 16,345 homes at quarter-end.
- Current asking data supports gross yields around 4.3% to 5.8% for many mainstream Warsaw units, with higher figures requiring careful checks on size, rent definition and condition.
- Budapest generally offers a lower euro entry price and more space or value-add choice, while Warsaw currently offers the stronger headline rental yield.
The Price Gap Is Negotiating Evidence
The NBP regional study put the average new-build asking price at PLN 18,488 per m² and the average transaction price at PLN 16,783. Asking prices rose 6.9% year on year, but completed prices rose only 2.4%. Sellers' expectations moved faster than the level buyers accepted.
The city average also hides a sharp district ladder. New-build transactions averaged PLN 24,513 per m² in Wola, PLN 19,324 in Mokotów, PLN 15,069 in Targówek and PLN 13,165 in Białołęka. The gap between a central employment corridor and an outer district is large enough to change both tenant demand and exit liquidity.
Completed Stock Creates a Local Buyer Advantage
CBRE and Tabelaofert.pl counted 16,345 new apartments for sale at the end of June, up 7.1% in three months. Of these, 3,344 were already complete. Some had been finished in late 2025. Developers also launched 4,753 homes in Q2, 66.8% more than in the previous quarter, and the new supply was 8.6% cheaper per square metre on average.
This is the local edge. A completed unit removes delivery risk and lets an investor inspect the exact light, outlook and finish. If it has been sitting through several sales campaigns, the useful negotiation may appear in fit-out, parking, storage or payment terms rather than the published apartment price.
Yield Still Supports the Warsaw Case
Global Property Guide's September 2026 asking-data sample placed Poland's average gross residential yield at 5.85%. Mainstream Warsaw examples ranged from about 4.32% for a Wola studio to around 5.83% for two-bedroom apartments in Mokotów. Outliers above that level should be checked for size, furnished rent, administrative charges and comparability.
Polish rental adverts often separate the owner's base rent from the administrative charge paid to the building or cooperative. Only the income retained by the owner belongs in the numerator of a gross-yield calculation. Vacancy, tax, management, maintenance and owner-paid charges still reduce the result.
| Warsaw signal | Q2 or Q3 2026 evidence | Investor reading |
|---|---|---|
| New-build asking price | PLN 18,488 per m² | Headline price |
| New-build transaction price | PLN 16,783 per m² | 10.2% below asking average |
| Completed unsold homes | 3,344 units | Inspectable stock and possible leverage |
| Typical gross yield | About 4.3% to 5.8% | Stronger than Prague, before costs |
| Development pipeline | 62.6% due in 2027 or 2028 | Delivery timing still matters |
Buy the District and the Handover Date
Białołęka and Targówek produced almost a quarter of both new-build supply and transactions in the NBP study. Włochy and Ursus added another 19.7% of sales. These districts offer lower entry prices, but transport and the immediate rental catchment decide whether the discount is real.
The pipeline is weighted toward later completion. Some 41.1% of available units were scheduled for 2027 and 21.5% for 2028. Buyers still favoured nearer handovers. That preference matters because a cheaper unit that cannot earn rent for eighteen months may not beat a completed apartment with a slightly higher headline price.
Small apartments also carried stronger relative demand. Units below 40 m² formed 24.1% of supply but 28.9% of transactions. The 40 to 60 m² band remained the largest part of the market. An efficient two-room layout near metro, tram or suburban rail therefore remains the most liquid investor brief.
Warsaw and Budapest Reward Different Buyers
Warsaw currently offers the stronger headline income case. Its typical gross asking yields sit above Prague and often above Budapest. The city's employment base, universities and internal migration support a deep tenant pool.
Budapest offers the stronger value entry. A euro buyer can usually access more floor area, more central historic stock or a larger refurbishment margin for the same capital. Budapest's three-bedroom asking yield was 5.63% in the same September comparison, below Warsaw's 8.87% city figure but well above Prague's 3.15%. The unusually strong forint also means that any later currency retreat could improve new euro buyers' purchasing power, though it would reduce the translated value of existing holdings.
Foreign Buyers Need to Check the Title
European Economic Area and Swiss buyers do not need a ministerial permit. Polish government guidance also exempts many purchases of an independent residential unit by other foreign buyers, subject to statutory exceptions. Separate ownership is generally easier to assess than a cooperative ownership right, which needs specific legal and financing review.
On resale, investors should budget for 2% PCC, Poland's civil-law transactions tax, unless a specific exemption applies. On new build, verify whether parking, storage and fit-out sit outside the apartment price. A notarial transfer does not replace independent review of the land and mortgage register, arrears, building works and any existing tenancy.
The Outlook Is Selective Rather Than Weak
The base case is moderate price growth, resilient rental demand and wider differences between projects. Falling rates or stronger credit growth could absorb the new supply faster. The warning signal would be completed inventory rising while rents and sales slow together.
Warsaw remains investable because demand is real. The opportunity in late 2026 is that supply has finally given buyers enough choice to be demanding. The best purchase is not the unit with the boldest yield calculation. It is the completed or near-complete apartment whose base rent, charges, title and transport connection still work after the sales incentive disappears.
Related PFC reading: What EUR 250,000 Buys in Warsaw | Budapest vs Warsaw | Gross vs Net Rental Yield
Newsletter: Get Place for Capital's European property analysis in your inbox.
Dieser Artikel dient allgemeinen Informationszwecken und stellt keine persönlichen Anlage-, Rechts- oder Steuerberatung dar.
Vergleichen Sie diesen Markt im PFC Property Investor Index →