Rome and Bucharest trigger the broadest physical-hazard screen in this 11-city comparison. Each has a medium or high flag in all five hazard families we checked. Yet Warsaw combines the highest estimated gross yield in the PFC Property Investor Index with only two such flags. The finding is not that risk follows return. It is that each market has a different route from physical hazard to investor cost.
A warm city is not automatically a poor investment. A river city is not automatically uninsurable. The useful question is narrower: which hazards deserve deeper checks before you choose the building, price the work and rely on an exit?
In brief
- Rome and Bucharest have five medium or high hazard flags across flood, heat, water scarcity, wildfire and earthquake screening.
- Athens, Lisbon and Zagreb have four. Their hazard mixes are different.
- Prague, Warsaw, Bratislava and Budapest have two flags each, but not the same two.
- There is no simple yield-for-risk pattern. Warsaw has the highest estimated gross yield at 5.59% and two flags. Rome has a 4.98% estimated gross yield and five.
- The city screen cannot price one building. The investor still needs the local hazard map, a technical inspection, a written insurance quote and a realistic adaptation budget.
The finding: physical risk does not move neatly with investment appeal
The PFC Property Investor Index compares 11 European residential property markets under one method. Its Current Investment Case includes buying power, estimated gross yield, acquisition costs and rental-entry conditions. Its Macro & Physical Resilience component combines four country-level macro inputs with one projected extreme-heat input.
We added a separate physical-hazard screen using the 2026 update of the World Bank GFDRR ThinkHazard tool. We checked five hazard families: flood, extreme heat, water scarcity, wildfire and earthquake. A flag means the urban or administrative area is rated Medium or High. For flood, we used the highest available rating across river, pluvial and coastal flood.
This produced a split result. Bucharest ranks first in the Current Investment Case at 87.70 and has five physical-hazard flags. Athens ranks third at 81.03 and has four. Warsaw ranks second at 81.04 but has only two. The data do not support a claim that higher yield or a stronger current investment case automatically means more physical risk.
| City | Current Investment Case | Estimated gross yield | Index resilience score | Medium or high hazard flags |
|---|---|---|---|---|
| Rome | 64.34 | 4.98% | 61.0 | 5 |
| Bucharest | 87.70 | 4.60% | 77.2 | 5 |
| Athens | 81.03 | 4.33% | 46.2 | 4 |
| Lisbon | 56.76 | 4.05% | 58.3 | 4 |
| Zagreb | 68.13 | 3.90% | 82.0 | 4 |
| Sofia | 80.90 | 4.04% | 84.9 | 3 |
| Valencia | 71.66 | 4.85% | 65.5 | 3 |
| Budapest | 78.59 | 4.30% | 64.5 | 2 |
| Bratislava | 69.08 | 3.81% | 78.6 | 2 |
| Prague | 58.10 | 3.33% | 80.5 | 2 |
| Warsaw | 81.04 | 5.59% | 79.1 | 2 |
The five-hazard matrix
| City | Flood | Heat | Water scarcity | Wildfire | Earthquake |
|---|---|---|---|---|---|
| Rome | High | Medium | High | High | Medium |
| Bucharest | Medium | Medium | Medium | High | Medium |
| Athens | Very low or none | Medium | High | High | High |
| Lisbon | High | Medium | High | High | Very low |
| Zagreb | High | Medium | Very low | Medium | Medium |
| Sofia | Very low or none | Medium | Very low | Medium | Medium |
| Valencia | Medium | Medium | Low | High | Low |
| Budapest | High | Low | Very low | High | Very low |
| Bratislava | High | Low | Very low | High | Low |
| Prague | Medium | Low | Very low | Medium | No hazard |
| Warsaw | Medium | Low | Very low | Medium | No hazard |
The pattern is more useful than one total. Rome combines flood, heat, water, wildfire and seismic flags. Bucharest has the same five-family breadth at different levels. Athens is driven by heat, water scarcity, wildfire and earthquake. Lisbon is driven by flood, heat, water scarcity and wildfire.
Budapest deserves an honest reading. Its Index resilience score is 64.5, below seven of the 11 markets, while its medium-or-high physical screen contains two families: river flood and wildfire. This is a filter signal, not a judgement on every Budapest property. It also shows why the Index’s Macro & Physical Resilience component cannot be read as a pure climate ranking. Four of its five inputs are macroeconomic.
Boundary choice matters too. ThinkHazard rates water scarcity Low for the Valencia urban area but High for the wider Comunitat Valenciana. That is not a data error. It is a warning that city, region, neighbourhood and parcel are different units of analysis.
What history shows, and what 2050 projections add
Historical evidence: the European Environment Agency estimates that weather and climate extremes caused EUR 822 billion of economic losses in the EU between 1980 and 2024. Floods accounted for 47% of the total. Average annual losses rose from EUR 8.6 billion in the 1980s to EUR 44.9 billion in 2020 to 2024. Less than 20% of the total was privately insured.
The figures do not prove that one city or building will suffer a loss. They show why insurance cannot be treated as an automatic transfer of every physical risk.
Recent climate record: the Copernicus European State of the Climate 2024 found that 2024 was Europe’s warmest year on record and tracked heat-stress days against the 1991 to 2020 reference period.
Future projection: the Joint Research Centre’s PESETA V work assesses regional impacts around 2050 under a 2°C global-warming scenario. It covers river and coastal floods, drought, cooling demand, transport damage, wildfire exposure and heat-related mortality. A separate JRC heat assessment finds that by 2050 heat-mortality hotspots are expected mainly in southern Spain, Italy and Greece, while eastern Europe also faces intensified warming.
The Climate-ADAPT review of 571 European cities projects more heatwave days in every city. Southern cities see the largest increase in heatwave days, while central European cities can experience some of the largest increases in heatwave temperature. Under the high-impact scenario, most cities see both drought and river-flood risk rise.
These projections describe future regional and city patterns. They are separate from the Index’s five-year score. They should not be presented as a forecast for the price or condition of one home.
How the hazard reaches the investor
| Hazard | Possible investor channel | Evidence to obtain before buying |
|---|---|---|
| Heat | Cooling capex, higher energy use, tenant discomfort, weaker demand for exposed top floors | Orientation, shading, insulation, cooling capacity, summer bills and energy certificate |
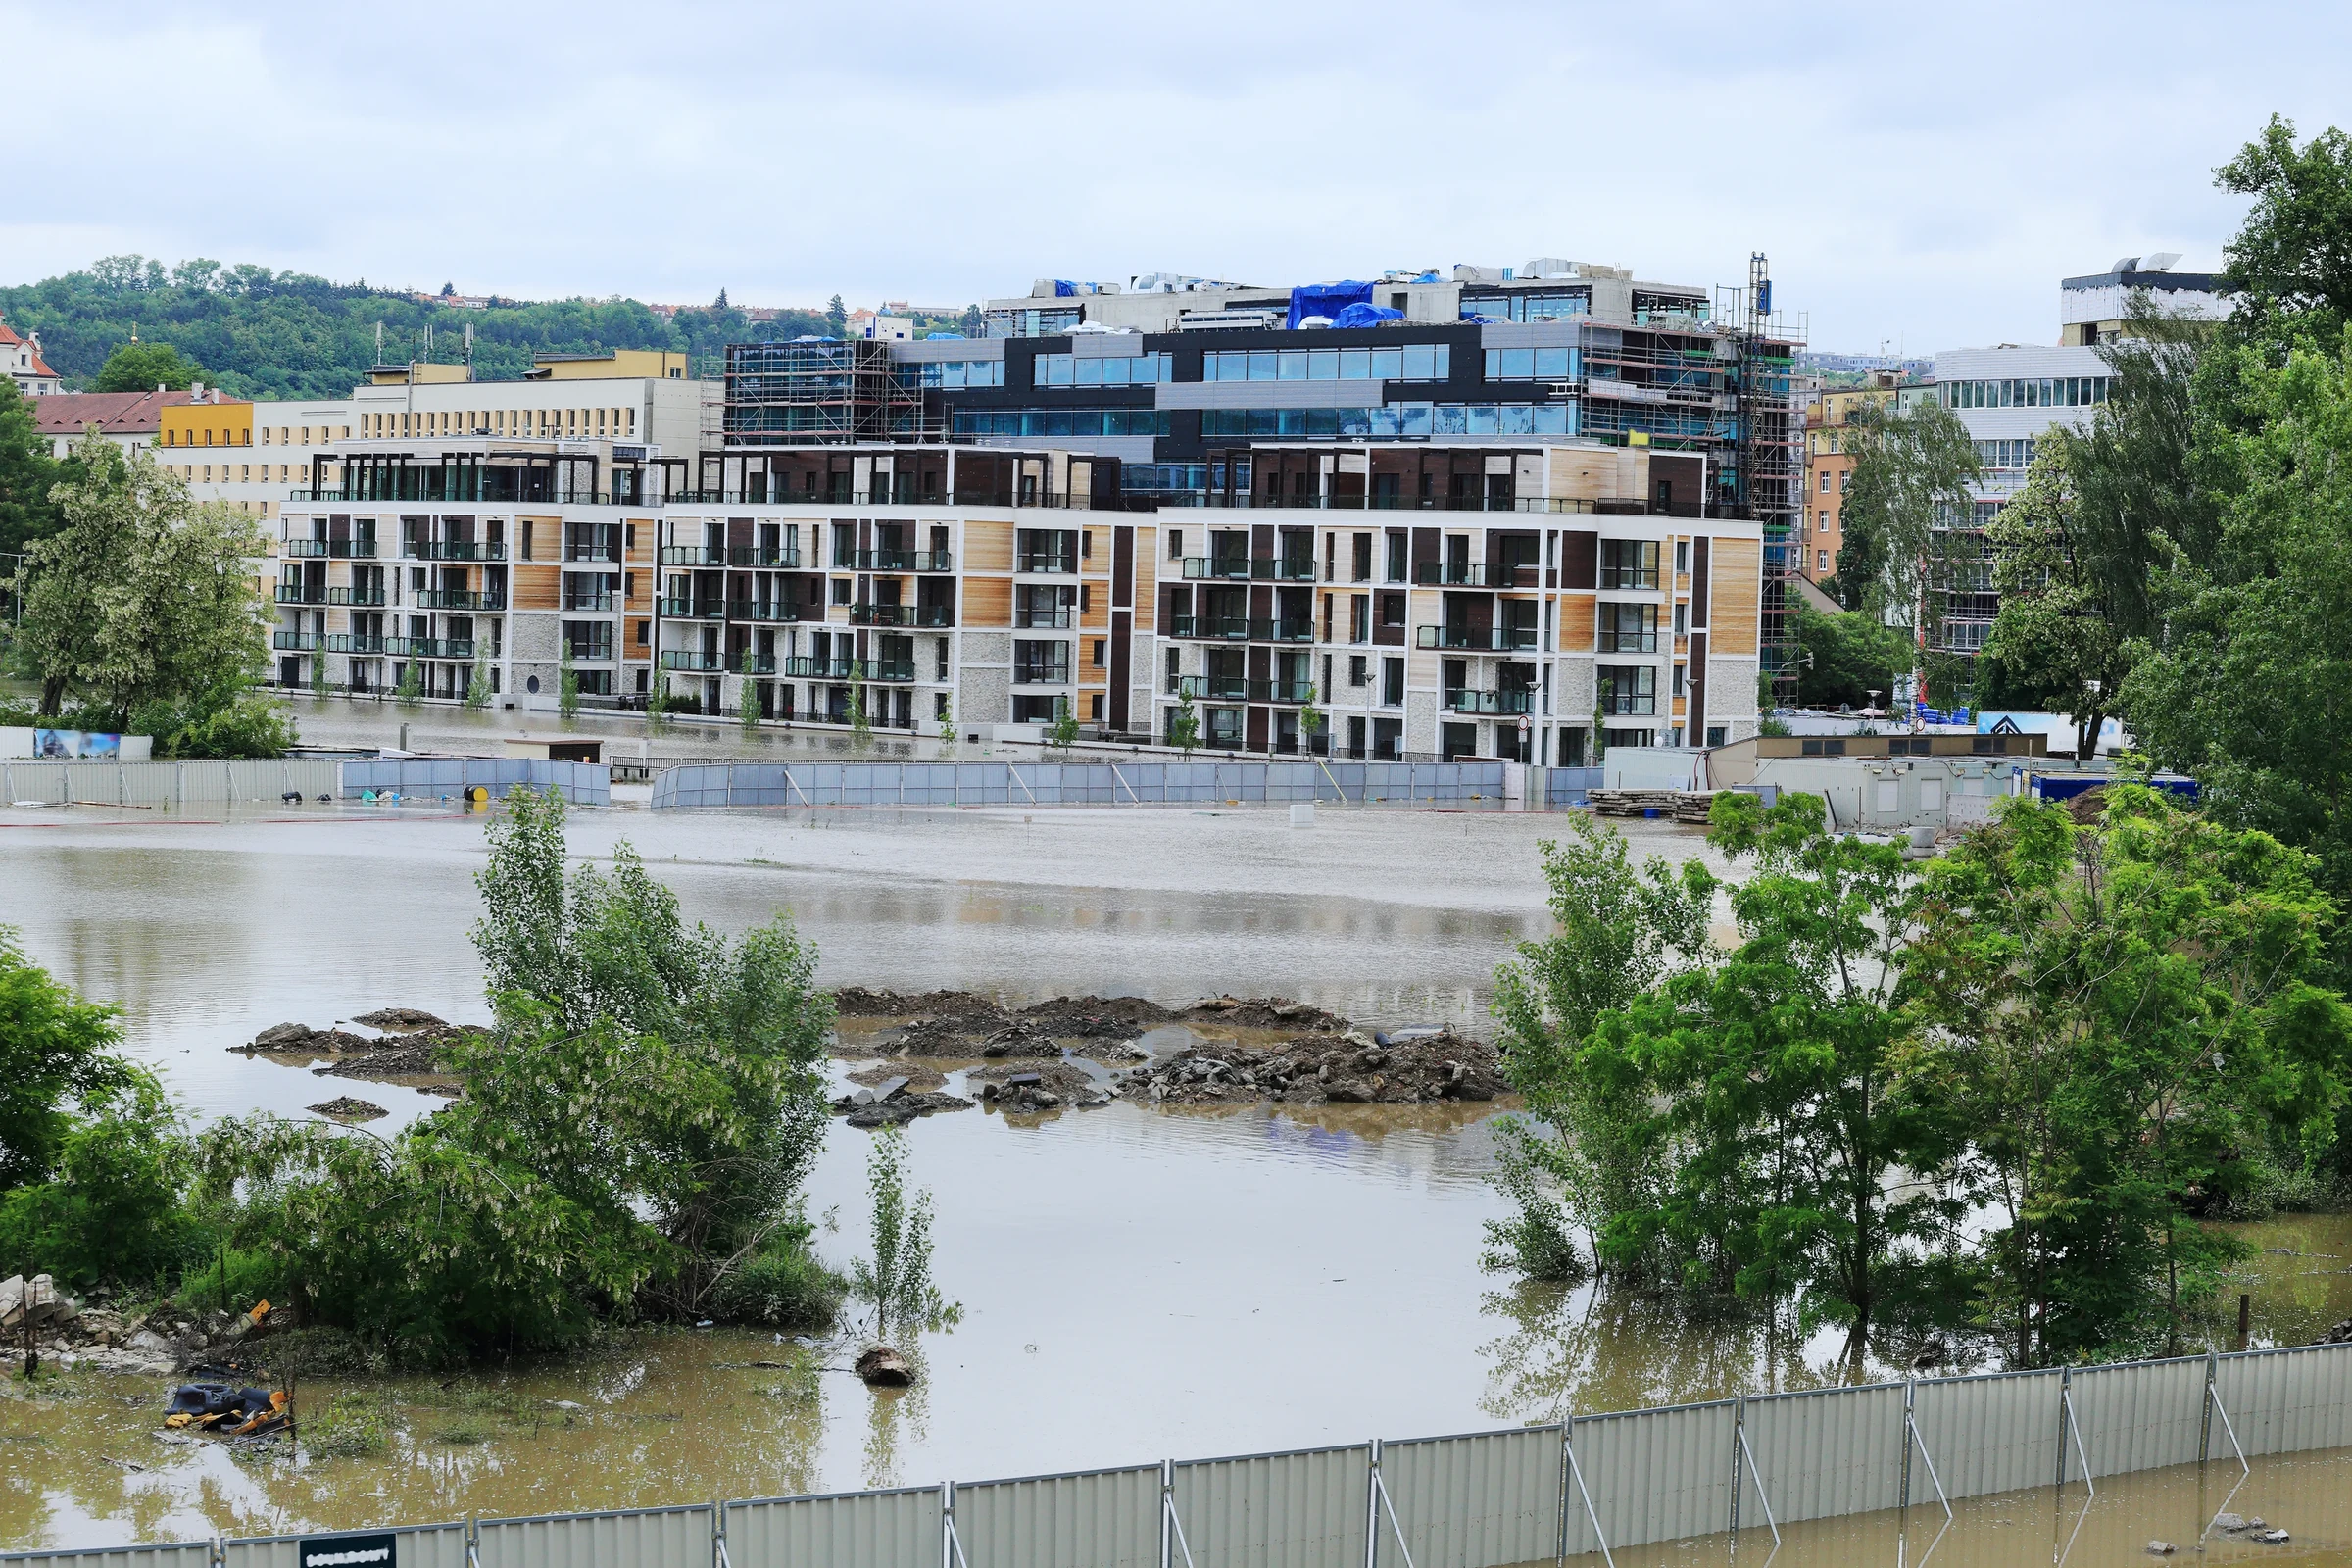
| Flood | Insurance exclusions, damaged basements and plant rooms, access disruption, valuation and lending friction | Official parcel map, floor level, drainage route, past claims and a property-specific insurance quote |
| Water scarcity and drought | Water restrictions, landscaping cost, soil movement and higher fire-weather exposure | Local water plan, soil information, crack history, vegetation and foundation survey |
| Wildfire | Direct damage, smoke, evacuation, insurance pricing and reduced buyer confidence at the urban edge | Wildland interface map, access route, vegetation management, facade and roof materials |
| Earthquake | Structural damage, retrofit cost, common-area liabilities, insurance and mortgage conditions | Construction year, structural system, retrofit records, association reserves and seismic map |
The financial path is rarely dramatic on day one. It can begin with a higher premium, an excluded peril, a cooling system, basement protection or a reserve-fund contribution. It can later affect vacancy, rent, refinancing and the number of buyers willing to accept the same risk.
Our guide to the hidden costs of buying property in Europe explains why these items belong in the acquisition budget. The cash-versus-mortgage guide shows why lender requirements can change the result even when the property price does not.
A four-document climate-risk test
Do not start with a generic checklist. Start with the two highest hazard flags for the city and collect four documents for the exact property:
- The local hazard-map extract showing the parcel or the smallest available area.
- A property-specific insurance quote listing flood, wildfire, subsidence, earthquake and water-damage exclusions.
- A priced adaptation item linked to the property, such as cooling, shading, drainage, flood barriers or structural work.
- An exit check from a local lender, valuer or comparable sale showing whether the hazard affects finance or resale liquidity.
If the city screen says High but the parcel map, building survey and insurance terms are clean, the property may still work. If the city screen says Low but the basement sits in a local flood route, the city label offers no protection.
The PFC view
The strongest finding is not a league table of safe and unsafe cities. It is the absence of a simple shortcut.
Rome and Bucharest need the broadest five-hazard screen. Athens and Lisbon also demand wide due diligence. Warsaw shows that a higher estimated yield does not automatically carry more physical flags. Zagreb shows that a strong Index resilience score can coexist with several physical hazards because most of that component is macroeconomic.
Use the PFC Property Investor Index to compare markets. Read the PFC methodology to understand the score. Then replace the city-level screen with local evidence before you price the building.
Download the PFC Property Investor Index 2026Q3 Private Investor Briefing.
This article provides general research, not personal investment, engineering, insurance, legal or tax advice. Hazard classifications are screening indicators for an urban or administrative area. They are not probabilities of loss for a specific building.